IVF Cost Planning: What to Budget for Before You Start Treatment
•
SCRC Editorial Team
•
7 min read
One of the first questions patients ask us is some version of: “How much is this actually going to cost?” It’s the right question to ask, and it deserves a straight answer.
The honest truth is that IVF pricing in the United States is genuinely complicated. Clinics quote base fees that rarely reflect what you’ll end up paying. Medications, genetic testing, frozen embryo transfers, and storage fees all get layered on top. And because most patients need more than one cycle, the number you see on a brochure can be a fraction of your real total.
At Southern California Reproductive Center (SCRC), we’ve been helping patients navigate this for over 25 years. We believe the most empowering thing we can do before you start treatment is make sure you understand exactly what you’re budgeting for. This guide walks through every major cost category, what’s commonly included (and excluded) in quoted prices, and how to build a realistic financial plan before your first cycle.
Key takeaway: A single all-in IVF cycle in the U.S. typically runs $23,000 to $30,000 once medications and standard add-ons are included. Because most patients need 2 to 3 cycles, a realistic total budget is $40,000 to $60,000 before insurance or financing.
What the Quoted “Base Fee” Actually Covers
When a clinic advertises an IVF price, they’re typically quoting the base clinical fee, which covers the core procedural work of a single cycle. Understanding what that includes (and what it doesn’t) is step one in building an accurate budget.
What’s usually included in a base IVF quote
Most base fees cover the following:
- Cycle monitoring: Ultrasounds and blood work during ovarian stimulation (roughly 10-14 days)
- Egg retrieval procedure: The surgical procedure to collect mature eggs
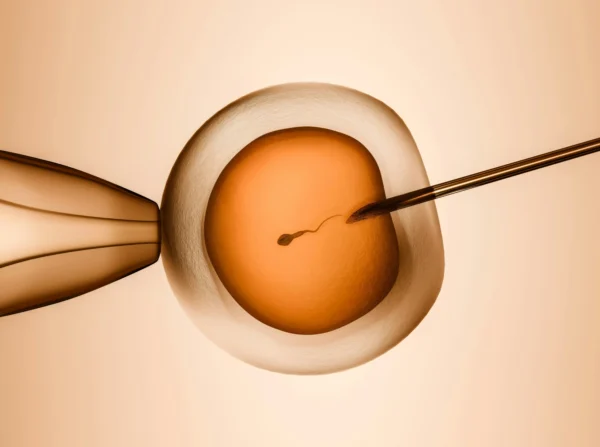
- Laboratory fertilization and embryo culture: Fertilizing eggs with sperm and growing embryos for 3-5 days
- One embryo transfer: Placing an embryo into the uterus (either fresh or frozen, depending on the clinic)
The base clinic professional fee typically runs $9,000 to $14,000 at most U.S. clinics, according to IVFcost.co, which tracks pricing across 452 clinic locations nationally.
What’s almost always billed on top
This is where the sticker shock happens. The following are rarely included in that base number:
- Fertility medications: $3,000 to $7,000 per cycle. This is the single biggest variable in the total cost.
- Anesthesia for egg retrieval: $800 to $2,500, often billed separately by an independent anesthesia group
- ICSI (intracytoplasmic sperm injection): $1,500 to $2,500, added when sperm quality is a factor or when genetic testing is planned
- Pre-cycle diagnostic testing: Bloodwork, semen analysis, and imaging before treatment begins
The real number: Once medications and the most common add-ons are included, a single complete IVF cycle in the U.S. runs approximately $23,000 to $30,000, per data compiled from published clinic fee schedules and ASRM cost surveys.
Genetic Testing: The Add-On That Changes the Math
Preimplantation genetic testing is one of the most consequential decisions in your IVF financial plan, both medically and financially. It’s worth understanding before you commit to a protocol.
PGT-A (preimplantation genetic testing for aneuploidy) screens embryos for chromosomal abnormalities before transfer. It’s one of the most commonly recommended add-ons, particularly for patients over 35, those with prior pregnancy loss, or anyone pursuing a freeze-all cycle. The cost structure has two components:
- Platform fee: $3,000 to $6,000 to set up and run the testing
- Per-embryo biopsy fee: $200 to $500 per embryo biopsied
If a cycle produces five viable blastocysts, the total genetic testing cost alone can reach $4,500 to $8,500. That’s a meaningful addition to the base cycle cost.
PGT-M (preimplantation genetic testing for monogenic disorders) tests for specific inherited conditions like cystic fibrosis, sickle cell disease, or BRCA mutations. It’s more complex and more expensive, typically running $4,500 to $7,500.
Is genetic testing worth the cost?
For many patients, yes. Transferring a chromosomally normal embryo significantly increases the likelihood of a successful pregnancy and reduces the risk of miscarriage. The American Society for Reproductive Medicine (ASRM) provides guidance on when PGT-A is most clinically appropriate, though it notes the decision should be individualized.
At SCRC, we offer genetic analysis through the Nucleus IVF+ network, which integrates advanced genetic testing directly into the treatment protocol. The goal is to give embryos the best possible chance of a successful transfer, which can reduce the number of cycles needed overall, and the total cost.
Frozen Embryo Transfers and Storage: The Ongoing Costs
Most IVF cycles today end with a freeze-all strategy rather than a fresh transfer. Embryos are cryopreserved, and the transfer happens in a separate, subsequent cycle. This approach reduces the risk of ovarian hyperstimulation syndrome (OHSS) and allows for genetic testing results to come back before transfer. It’s generally better medicine. It’s also an additional billing event.
Frozen embryo transfer (FET) costs
A frozen embryo transfer cycle involves its own medications, monitoring, and the transfer procedure itself. Budget:
- FET cycle (medications, monitoring, transfer): $3,000 to $6,000
- Cryopreservation fee (initial): $500 to $1,500 at the time of freezing
- Annual embryo storage: $500 to $1,000 per year, billed yearly until embryos are used, discarded, or donated
If you freeze embryos after your first retrieval and transfer one in a subsequent cycle, you’re already looking at two billing events before you’ve had a single transfer attempt.
What happens to unused embryos?
This is a question patients often don’t think about at the budgeting stage, but it matters. If you have remaining embryos after a successful pregnancy, ongoing storage fees continue until you make a decision about them. Options include continued storage, donating to another family, donating to research, or discarding. Each has different cost implications, and some have legal or ethical dimensions worth discussing with your care team.
Bottom line: Build annual embryo storage into your budget from the start, even if you hope to only need one cycle.
A Realistic IVF Budget by Scenario
The range you see quoted online ($15,000 to $30,000) is technically accurate for a single cycle, but it doesn’t reflect how most patients experience IVF financially. Here’s a more honest look at what different treatment paths actually cost, based on current U.S. pricing data.
| Scenario | Estimated Total Cost |
|---|---|
| Fresh single-transfer cycle, no PGT | $17,000 to $30,000 |
| Freeze-all + first FET, no PGT | $22,000 to $37,000 |
| Freeze-all + PGT-A + first FET | $27,000 to $45,000 |
| Two complete cycles (average need) | $40,000 to $60,000 |
| Donor egg IVF cycle | $25,000 to $45,000 |
Ranges reflect clinic fees, medications, and standard add-ons. Source: IVFcost.co, compiled from 452 clinic locations.
Why most patients need more than one cycle
According to CDC data on ART outcomes, IVF success rates per cycle vary significantly by age. Patients under 35 have the highest per-cycle success rates, but even in the best-case scenarios, a single retrieval doesn’t guarantee a live birth. The average patient in the U.S. needs 2.3 to 2.7 cycles to achieve a successful pregnancy.
This is the number the industry doesn’t advertise, and it’s the most important one for budgeting purposes.
For patients in California: California does not have a state IVF insurance mandate, unlike states such as Massachusetts, New York, or Illinois. This means most patients in Southern California are paying out of pocket or relying on employer benefits. Always confirm your plan type (fully-insured vs. self-insured/ERISA) before assuming coverage applies.
Insurance, Employer Benefits, and Financing Options
The financial picture for IVF has changed significantly over the last several years. While California has no state mandate requiring insurers to cover IVF, there are more pathways to coverage and financing than most patients realize.
Employer-sponsored fertility benefits
Employer coverage has expanded rapidly. According to data tracked by RESOLVE: The National Infertility Association, 50% of employers with 500 or more employees now offer some form of fertility benefit, up from 27% in 2020. The median lifetime cap is around $20,000, which covers roughly one complete cycle.
Before assuming you have no coverage:
- Review your benefits documentation specifically for “fertility treatment,” “ART,” or “IVF”
- Ask your HR department whether your plan is fully-insured or self-insured (ERISA), since state mandates only apply to fully-insured plans
- Check whether medications are covered under a separate pharmacy benefit
Financing and payment plans
For patients paying out of pocket, several financing structures are available:
- Medical financing loans: Companies like CapexMD and Prosper Healthcare Lending offer fertility-specific loans with deferred interest periods
- Multi-cycle packages: Some clinics offer bundled pricing for two or three cycles at a reduced per-cycle rate
- Shared risk / refund programs: These programs charge a higher upfront fee but refund a portion if treatment is unsuccessful after a defined number of cycles. They’re not right for everyone, but worth asking about
Flexible spending and health savings accounts
IVF treatment qualifies as a medical expense under IRS guidelines, meaning FSA and HSA funds can be applied to most treatment costs, including medications. If your employer offers these accounts, maximizing contributions before starting treatment is one of the most straightforward ways to reduce your after-tax cost.
Questions to Ask Before You Commit to a Clinic
Not all IVF quotes are created equal. The difference between a $12,000 quote and a $20,000 quote at two different clinics often comes down to what each one includes. Before signing a financial agreement, get clear answers to these questions in writing.
- Does the quoted price include medications? Most base fees do not. Ask for a separate medication estimate based on your anticipated protocol.
- Is anesthesia included or billed separately? This is often a surprise bill from an independent anesthesiology group.
- What does a frozen embryo transfer cost? If the clinic recommends a freeze-all protocol, this is a near-certain additional expense.
- Are monitoring appointments (ultrasounds and bloodwork) included? Most clinics include these, but confirm.
- What is your ICSI policy? Some clinics apply ICSI to all cycles; others use it selectively. Understand when and why it would be added to your cycle.
- What are your success rates for my age group? Verified outcomes data is available through SART (the Society for Assisted Reproductive Technology), which publishes clinic-level success rates annually. A clinic with stronger outcomes may cost more per cycle but fewer cycles overall.
- Do you offer multi-cycle pricing or a refund program? If you’re likely to need more than one cycle, bundled pricing can reduce the total cost meaningfully.
The right clinic isn’t always the cheapest one. A lower per-cycle fee means little if the clinic’s success rates require more cycles to achieve a pregnancy. Factor outcomes data into your financial planning, not just the quoted price.
Starting Your IVF Journey with a Clear Financial Plan
IVF is one of the most significant financial decisions most patients will make. The emotional weight of that is real, and we don’t take it lightly. What we’ve seen over 25 years is that patients who go into treatment with a realistic financial picture, including the possibility of multiple cycles, are better prepared to make clear-headed decisions along the way.
The goal of this guide isn’t to make IVF feel more expensive than it is. It’s to make sure the number in your head matches what you’ll actually encounter. Surprises in the middle of treatment are the hardest kind.
If you’re considering IVF and want to understand what costs would look like for your specific situation, the best next step is a consultation with one of our physicians. We’ll review your diagnostic workup, discuss the protocol most appropriate for your case, and walk you through a detailed cost estimate before you make any commitments.
Schedule a consultation at SCRC to get a personalized financial and treatment plan from a team that has been doing this for over 25 years, in Beverly Hills and Santa Barbara.
Disclaimer: This article is for informational purposes only and does not constitute medical advice. Consult a board-certified Reproductive Endocrinologist for personalized guidance about your treatment.